 Ethereum market price and chart holders can participate in proof-of-stake through several arrangements, but the word ‘staking’ does not describe a single risk profile. Native validator participation, delegated operations and liquid staking pools differ in custody, accessibility and liquidity. A liquid staking token can provide an asset that trades while ETH remains committed to validation, but that flexibility introduces exposure beyond the Ethereum protocol itself.
Ethereum.org’s pooled-staking explanation distinguishes solo staking, staking services, pooled staking and opaque custodial products. It says solo operators retain direct control while pooled structures require reliance on other parties, contracts or operational systems. Investors comparing quoted yields should identify what actually generates the reward and who can change the arrangement.
How native staking works
In solo staking, an operator uses validator infrastructure to participate directly in Ethereum’s consensus process. The operator is responsible for keeping software functioning, securing signing credentials and following network rules. Rewards can accrue for correct participation, while missed duties and provably conflicting signatures can trigger penalties. The amount staked, rewards and withdrawal arrangements must be assessed under current protocol rules.
Not everyone wants to manage validator equipment. A staking-as-a-service arrangement may let an owner retain withdrawal control while outsourcing operations. That reduces maintenance work but leaves the owner dependent on the service’s reliability, security and fee structure. Custodial exchange products differ further because clients may hold an account claim rather than direct validator control.
What liquid staking adds
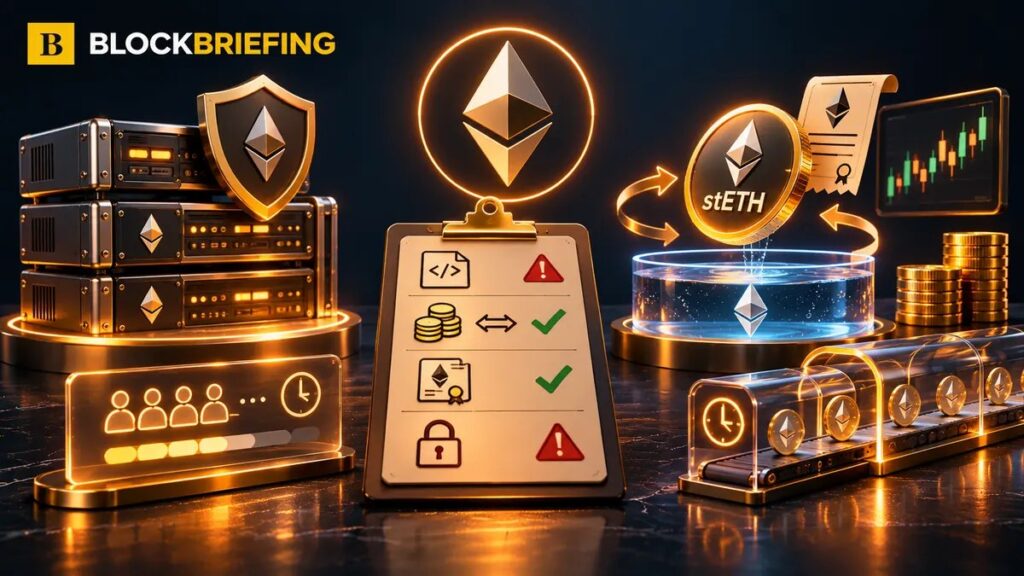
A liquid staking pool typically receives deposited ETH and issues a receipt-like token representing a claim under its protocol rules. The token may be transferable, usable in decentralized finance or sold before a protocol redemption is completed. Its exchange price is determined by buyers and sellers, not guaranteed to equal one ETH at every instant.
Ethereum.org identifies additional smart-contract, market-liquidity, governance and operator-concentration risks for liquid staking tokens. A contract exploit can affect claims; a redemption queue can slow access to underlying ETH; and thin trading can force someone who needs immediate cash to accept a discount. A high advertised yield cannot remove those risks.
Withdrawal timing and liquidity
Ethereum’s withdrawal documentation explains that validator exits pass through network processes, whereas different credential types affect routine reward sweeps and compounding. A pool’s internal exit process and token redemption mechanism can introduce additional delays. Selling a liquid staking token on an exchange may be faster, but it substitutes market execution risk for waiting on the protocol.
The underlying ETH can remain exposed to slashing or inactivity penalties while the receipt token trades. Some pools distribute losses across participants. Liquid staking tokens used as collateral introduce still another layer: changes in market value can trigger liquidation even without a direct validator failure. Users should identify each layer separately rather than comparing two annual percentage figures as though they were equivalent.
How to compare options responsibly
Review who holds withdrawal rights, the exact contract addresses, operator diversity, audit disclosures, fees, expected exit time, token liquidity and any collateral reuse. Read whether rewards are protocol-based or produced through lending or trading. A cautious decision compares the whole custody and settlement chain, including the possibility that funds cannot be withdrawn on demand. This guide is educational rather than a recommendation to stake.
Interpreting the quoted staking yield
A quoted annual percentage rate is a model or historical estimate, not a guaranteed payment. Ethereum consensus rewards depend on network participation and effective stake, while provider returns may be stated after or before fees. Some liquid tokens express accrued rewards through an increasing exchange rate rather than a visibly growing token balance. Compare yields using the same time period and fee assumptions and account for gas costs, redemption expenses and exchange execution. A superficially higher rate may compensate for exposures that do not exist in direct validation.
Liquidity versus redemption rights
Tradable receipt tokens can be sold on decentralized or centralized markets, sometimes before a validator exit could finish. That convenience depends on available buyers and market depth. A forced sale in a thin market may occur at a meaningful discount to the value of the underlying stake. Native redemption instead depends on the protocol’s withdrawal queue and the staking arrangement’s own processing. These mechanisms should be analyzed separately: one provides market liquidity when trading is possible, and the other governs an eventual claim to underlying ETH.
Smart contracts, upgrades and concentration
Liquid staking protocols can rely on deposit contracts, token issuance logic, accounting processes and withdrawal contracts. Each additional contract or privileged administrator may introduce new failure modes. Operators might be concentrated among a limited set of infrastructure providers, cloud services or geographies. That concentration affects both operational continuity and network decentralization. An audit can identify certain implementation issues but is not a promise that future upgrades, governance decisions or undiscovered vulnerabilities will be harmless. Readers should inspect published contract addresses and current upgrade authorities.
Collateral loops amplify risk
A person who deposits ETH, receives a liquid staking token and then borrows against that token has added lending-market risk to staking risk. Falling collateral value can trigger liquidation without any consensus-layer slashing. Repeated borrowing and redepositing can amplify both the nominal yield and the amount at risk. The resulting return is not simply ‘staking yield’: it incorporates borrowing costs, price discrepancies, oracle behavior and liquidation incentives. A cautious comparison should model a rapid receipt-token discount and a temporary inability to redeem.
Questions to ask a provider
Determine whether the product is custodial, whether holders retain withdrawal rights, what fees apply, and how rewards and penalties are allocated. Identify validator operators, smart-contract audits, withdrawal delays and how an emergency pause might work. Read what happens if a token loses its peg or if the provider ceases operations. Treat claims of ‘instant unstaking’ as statements about available secondary-market buyers unless the provider explicitly guarantees another mechanism with documented terms. The goal is to understand the full chain of dependencies, not merely select the largest advertised yield.