Bitmine Immersion Technologies reported a $6.31 billion net loss for the fiscal year ended August 31, 2026. The headline number is enormous. Yet a review of the company’s Form 10-K, filed with the US Securities and Exchange Commission on November 10, shows that the most useful way to assess the Bitmine Ethereum market price and chart treasury strategy is to examine several different figures together: unrealized asset losses, operating cash use, financing proceeds, and the expansion of outstanding shares.
BlockBriefing reviewed the filing’s consolidated statements, cash-flow disclosures, capital-raising discussion and cryptocurrency holdings tables. The arithmetic below is calculated from company-reported figures. The records establish material financial risks; they do not, by themselves, demonstrate wrongdoing or predict future returns.
Why The Headline Loss Was Mostly Noncash Accounting
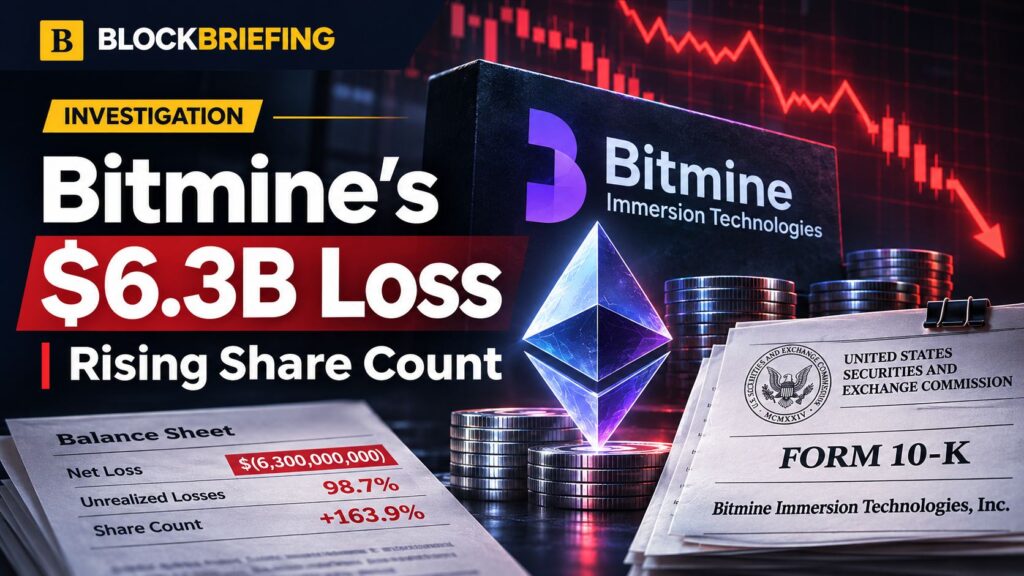
Bitmine recorded a fiscal 2026 consolidated net loss of $6,313,386,000, compared with a $348,577,000 net profit a year earlier. Its statements attribute $6,229,064,000 to unrealized fair-value losses on digital assets held. That category equals 98.7% of the reported net loss in absolute dollar terms, based on BlockBriefing’s calculation.
Because the company’s cryptocurrencies are measured at fair value, price changes can pass through earnings even when coins have not been sold. The unrealized loss is therefore not a claim that Bitmine transferred $6.23 billion in cash to cover a trading deficit. It is, however, an economically meaningful decline in the recognized value of assets on its balance sheet, which can influence investor confidence and access to capital.
At August 31, the filing lists 5,901,837 ETH valued at approximately $14.56 billion and 211 BTC market price and chart worth approximately $16.6 million. The ETH holdings’ disclosed cost basis was about $19.95 billion. The difference between year-end cost basis and fair value is not identical to the full-year unrealized-loss line because holdings, acquisition timing and accounting movements differ.
Operating Cash Outflows Point Beyond Simple Paper Losses
Reading only the noncash-loss figure would miss a separate finding. The cash-flow statement reports $305.15 million used in operating activities during fiscal 2026, up from $4.15 million the year before. This comparison identifies operating cash use independent of whether digital-asset valuation changes were realized.
Bitmine also reported approximately $12.55 billion in cash spent purchasing digital assets and $12.86 billion in net investing cash outflows for the fiscal year. Buying a crypto asset is ordinarily classified in investing cash flows rather than operating cash flows, so these categories should not be added together and labeled operating losses.
The company disclosed cash and cash equivalents of approximately $545 million at its fiscal year-end and working capital of about $528 million. Those balances must be considered alongside near-term commitments, further operating spending and any prospective financing. Neither the reported operating cash use nor the asset purchases alone establish insolvency.
Share Issuance Changed The Company Ownership Denominator Significantly
One of the largest changes in Bitmine’s filing is its shareholder base. The company reported 232,412,324 common shares outstanding on August 31, 2025, rising to 613,267,022 on August 31, 2026. The difference is 380,854,698 shares, an increase of approximately 163.9% in shares outstanding over the year.
The company said it sold 395,136,273 shares through an at-the-market offering program, raising about $13.20 billion in gross proceeds and approximately $12.94 billion in net proceeds. Its filings also describe additional financing routes. Separately, it repurchased about 20.8 million common shares for $353.8 million. These separate transactions should not be compressed into a single claim that every new share was issued at the same price or for the same purpose.
For context, if a hypothetical investor held the same number of common shares at both dates, and no other rights changed, that holding would represent about 37.9% of its previous fraction of the expanded share count. That illustrates the ownership-denominator effect, not a calculated loss in the share’s market value. New money raised also bought assets and helped fund the strategy; dilution metrics without asset-per-share analysis are incomplete.
Staking Revenue Grew But Remained Closely ETH Dependent
The company generated $124.81 million in fiscal 2026 revenue, of which $121.36 million came from staking and validation. BlockBriefing calculates that staking accounted for roughly 97.2% of revenue. The filing also identifies approximately $112.66 million in noncash staking and validation revenue within cash-flow reconciliation, reflecting the treatment of digital-asset rewards.
These figures show that the company’s reported revenue is concentrated in a cryptocurrency-based activity. While staking can produce recurring ETH-denominated rewards, their dollar value may fluctuate with token prices, and yields can change with network conditions. Validator operations can also face downtime or penalties. A growth narrative built solely on ETH holdings or staking income obscures these sensitivities.
Revenue should not be mistaken for free cash flow. Expenses, infrastructure spending, liquidity needs and any financing commitments still affect what can be distributed or reinvested. Even rapid token accumulation does not guarantee greater economic exposure per share if the share denominator rises at a different rate.
Other Financial Exposures Complicate The Treasury Market Narrative
The filing records an additional $143.67 million net loss on derivative contracts, while a $257.86 million gain from changes in the fair value of warrant liabilities moved results in the opposite direction. These items demonstrate why focusing on a single mark-to-market line can misrepresent the complete income statement.
Derivatives and warrants are not interchangeable with the core ETH holdings, and their reported net accounting effects should not be described automatically as cash receipts or payments. The company said it had no open derivative contracts at fiscal year-end, but that does not erase the effect of contracts used earlier in the period.
Investors following the Bitmine Ethereum treasury model must also account for preferred stock, warrants, possible future issuance, transaction costs and contractual rights that can affect equity holders differently. The headline amount of crypto owned is only one element of the valuation equation.
What The SEC Filing Does And Cannot Establish
This investigation is a documentary analysis of public company disclosures, not a forensic blockchain audit. It verifies what Bitmine reported in an SEC filing and calculates ratios from those statements. BlockBriefing has not independently matched every cryptocurrency address to the reported balances, examined nonpublic custody records or verified future staking rewards.
The annual report covers the fiscal year ended August 31. Later company announcements may contain newer ETH holdings, but they cannot be substituted for the year-end balance sheet without identifying the different dates. In particular, using a November total beside August financial statements to infer an August asset-per-share value would produce a misleading comparison.
Nor do the disclosed losses prove improper conduct. A crypto treasury company may intentionally accept substantial price volatility, issue shares and retain assets under a board-approved strategy. The appropriate question for investors is whether the resulting assets, cash requirements, ownership claims and financing terms justify the risks and valuation.
How Shareholders Can Evaluate The Next Filing Period
Four disclosure checkpoints will help determine whether the strategy is creating or eroding value for continuing shareholders. First, monitor the number of ETH and the independently defined net asset value per fully diluted share. Second, compare new fundraising proceeds with the increase in reported crypto holdings. Third, track operating cash use against liquid resources and commitments. Fourth, distinguish changes in fair value from realized gains, realized losses and cash receipts.
The company reported enough data to show that its ownership denominator expanded rapidly while ETH price movements overwhelmed its income statement. Whether future financing and staking can offset those pressures remains an open financial question.
Methodology and sources: BlockBriefing reviewed Bitmine Immersion Technologies’ fiscal 2026 SEC Form 10-K, including the statements of operations, cash flows, stockholders’ equity, financial note disclosures and management discussion. Original calculations: unrealized loss divided by the absolute value of net loss (98.7%); staking revenue divided by total revenue (97.2%); percentage change in outstanding common shares (163.9%). All financial amounts are fiscal-year figures unless otherwise stated; rounded totals may differ.