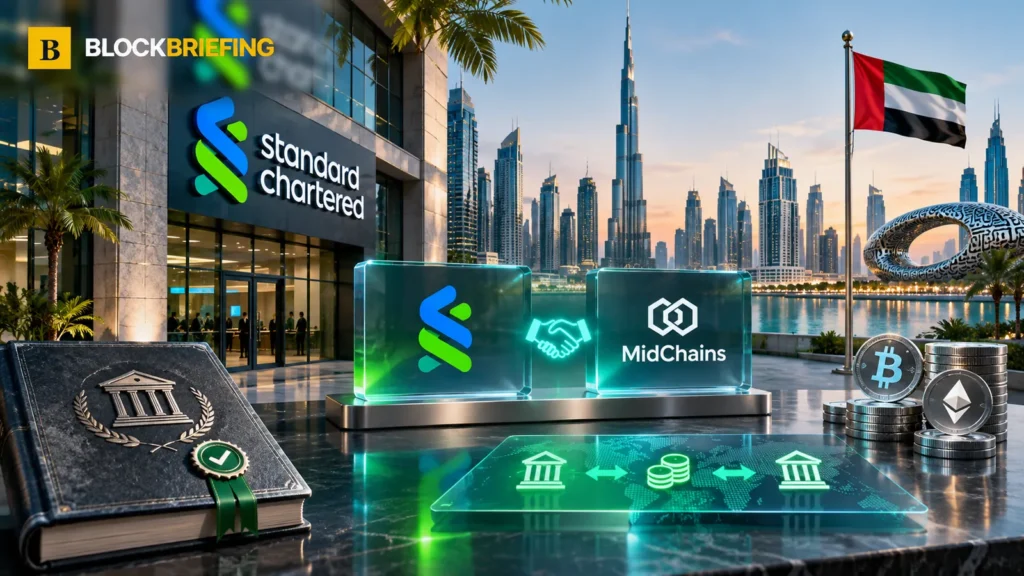
Standard Chartered has agreed to provide fiat settlement and account services to Dubai-based crypto broker MidChains, adding conventional banking infrastructure to the firm’s digital asset operations. The November 12 partnership includes segregated client-money accounts and correspondent banking services for eligible institutional activity.
In their joint announcement, the companies described the arrangement as support for the existing regulated brokerage business. MidChains says it is licensed by Dubai’s Virtual Assets Regulatory Authority. Neither party announced that the bank had acquired the platform or guaranteed its trades.
Banking services will support fiat settlement for clients
Rola Abu Manneh, Standard Chartered’s chief executive for the UAE, Middle East and Pakistan, described the relationship as an application of the country’s digital asset regulatory framework. The executive’s statement focused on support for institutional operations, including cash settlement and account services, rather than trading revenues or forecasts for cryptocurrency prices.
MidChains chief executive Basil Al Askari argued that institutional clients need a practical connection between traditional financial infrastructure and digital asset markets. For a broker, such a connection can matter when customers deposit fiat, withdraw proceeds or move funds between counterparties. These processes are often less visible than token trading but can determine whether a venue operates smoothly.
Segregated client accounts require independent operational controls
Segregated client-money accounts are intended to keep client balances distinguishable from a company’s operational funds. That does not, on its own, establish how accounts are reconciled, what protection exists if a service provider fails or whether any individual balance qualifies for deposit insurance. The announcement offered no independently reviewed account figures or customer asset reports.
Correspondent banking can support transfers through other institutions and currencies. It can also introduce additional compliance checks, processing chains and operating dependencies. The agreement describes access to a set of banking capabilities, not a guarantee that every transfer will clear immediately or at a fixed cost.
Deal terms leave commercial scale and rollout unanswered
The partners did not disclose expected transaction volumes, fees, revenue contributions, the number of participating institutions or the precise timetable for each service. Those omissions make it difficult to quantify the deal’s eventual business impact. Assertions that the arrangement has already moved large amounts of crypto-linked capital would require evidence beyond the press release.
Dubai has become an important testing ground for institutions offering regulated digital asset services. The MidChains agreement gives one example of how traditional banking functions may support those businesses. Its significance will depend on implemented services, customer adoption and continuing compliance, rather than on the partnership label alone.
The release does not identify expected volumes, transaction charges or a measurable reduction in settlement time. It also does not specify the exact customer protections attached to each banking arrangement. Those details would be needed before drawing conclusions about the financial impact of the partnership.
BlockBriefing previously reported on Deutsche Bank’s institutional crypto custody services, a separate banking model with different responsibilities. Its crypto custody explainer sets out why control over customer assets and access to a bank account are not the same thing. The MidChains partnership concerns services for a regulated intermediary, not the removal of digital asset risks.